 Debtless
The short answer
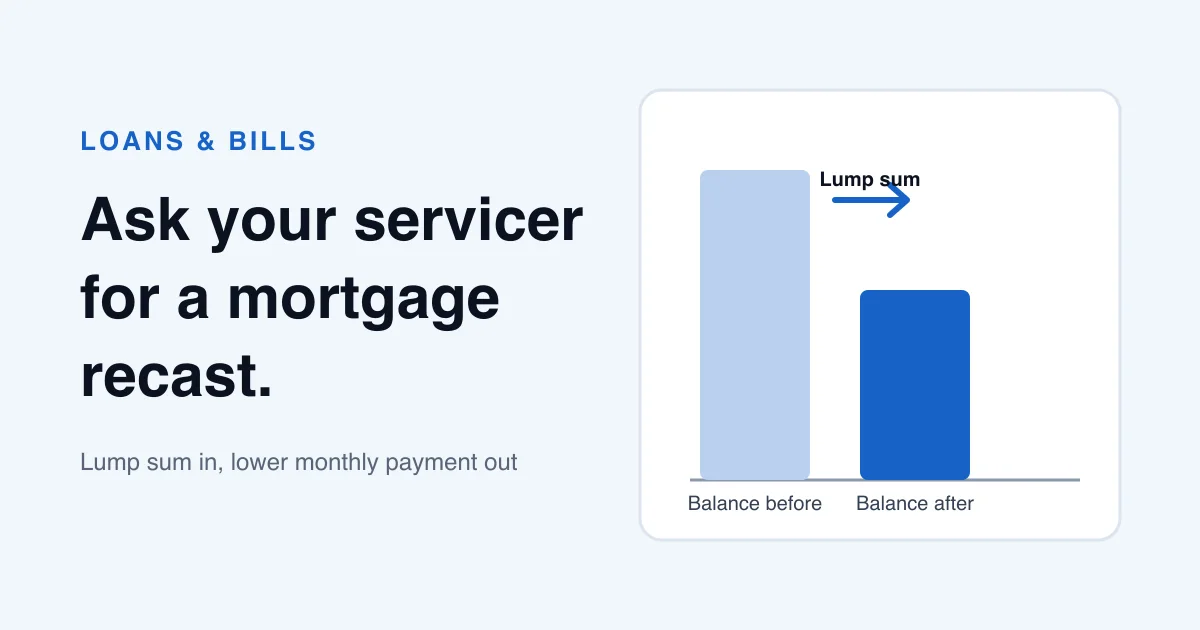
A mortgage recast takes your remaining balance after a lump-sum principal payment and spreads it over the remaining term at the same interest rate, so the monthly payment drops while the payoff date stays put. To ask for one, confirm that your loan type is eligible, get the minimum lump sum and any fee in writing, and see the new payment before you send the money. Chase says FHA, VA and USDA loans cannot be recast, PennyMac requires a lump sum of at least $10,000, and Chase lists no minimum.
Is your loan type eligible for a recast?
The servicer is the company that sends your statements and collects your payments, and it may not be the company that made the loan. The servicer applies the investor rules for your loan, which is why the answer can differ from one loan to the next.
Check eligibility first. It can end the request before any money moves. Chase's recast page says that "FHA, VA and USDA loans are not eligible for a recast." The same page says availability depends on investor guidelines and can change without notice. Call the servicer, ask whether your specific loan can be recast, and ask where the policy is written down. If the answer is no, the lump sum still lowers your balance, but you keep the old payment and the loan ends sooner.
What should you ask before you send the lump sum?
Get five answers before the money moves, and get them in writing. Each one can change whether the recast is worth doing, and the first two are where lenders differ most. A short message covers the list: "I plan to make a $12,000 principal payment on my loan. Please tell me whether a recast is available for this loan, the minimum principal amount, any fee, and the new monthly payment on the resulting balance, in writing." Send it through the servicer's online messages or by mail, so you have a dated record.
- The minimum lump sum. PennyMac's recast FAQ says the principal payment must be at least $10,000.00. Chase's page lists no minimum, but warns that a small principal reduction will not significantly lower the payment.
- Any fee. PennyMac's FAQ says no fee is charged for the recast. Chase's page says fees may apply and gives no amount, so ask for the number in writing.
- The new payment, calculated on the exact balance you will have after the lump sum, at your current rate and remaining term.
- When the recast takes effect, and how the lump sum posts, including whether it goes straight to principal.
- How to send the money. Get every answer in writing, then pay by the method the servicer names.
How much does a $12,000 lump sum change the payment?
Take a hypothetical loan with a $185,000 balance at 5.875%, with 276 months (23 years) left. The original payment is $1,223.58 a month. Send $12,000 as a lump sum, and the balance drops to $173,000. A recast spreads that $173,000 over the same 276 months at the same rate, so the payment falls to $1,144.21, a drop of $79.37 a month. The loan still ends in month 276.
The same $12,000 can work the other way. Keep paying $1,223.58 and the balance reaches zero in 242 months, 34 months sooner. The table compares the three paths. Interest figures leave out the $12,000 itself, and they use the standard amortization formula. If you are comparing a lump sum with steady extra payments instead, the mortgage pay-down worked example runs those two paths on a different loan.
| Option | Monthly payment | Months to payoff | Interest from today | Interest saved vs. no lump sum |
|---|---|---|---|---|
| No lump sum, $185,000 balance | $1,223.58 | 276 | about $152,708 | none |
| Lump sum, then recast | $1,144.21 | 276 | about $142,803 | about $9,905 |
| Lump sum, same payment | $1,223.58 | 242 | about $122,217 | about $30,491 |
Hypothetical loan at 5.875% with 276 months remaining. The recast keeps the end date and lowers the bill. Keeping the payment finishes the loan sooner and saves more interest.
How do you check the recast letter against your records?
After the effective date, read the first statement and compare three numbers: the monthly payment, the balance and the remaining term. The payment should match the written figure. The balance should match your records, less the lump sum and any payments since. If the payment has not changed, call the servicer with the letter in hand. For the schedule side of this, Mortgage Payoff Calendar: A Checklist shows how to turn the new payment into milestones you can check every year.
Worked example · illustrative numbers
Example: which path fits a tight monthly budget
Suppose the household can free up $79 a month but would rather finish the loan 34 months early. A recast gives the first. Keeping the old payment gives the second, and it also saves about $20,600 more in interest than the recast does ($30,491 minus $9,905). Neither choice changes the rate. The difference is whether the money you save shows up as cash flow now or as a shorter loan.
Put this into practice with Debtless
Debtless does not contact your servicer, process a recast or move money. In the free iPhone app you can enter the mortgage's balance, rate, minimum payment and due date, then record the new payment and watch the projected payoff date change. Keep the servicer's written numbers as the source of truth, because the app projects only from what you type.
Common questions
Is a recast the same as a refinance?
No. A refinance replaces your loan with a new one, which usually involves new underwriting and closing costs. A recast keeps your current loan, rate and end date, and recalculates only the payment on the remaining balance.
Does a recast change my interest rate?
Not according to Chase's recast page, which says a recast keeps your current interest rate. Only the payment changes.
Will a recast shorten my payoff date?
No. Chase describes a recast as spreading the remaining balance over the remaining term, so the end date stays where it was. To finish sooner, keep the old payment after the lump sum.
What if my lump sum is below the servicer's minimum?
Ask what the servicer offers for a smaller amount, and ask whether a small reduction is worth the request. Chase warns that a small principal reduction will not significantly lower the payment.
Sources & further reading
- Chase: Recast your mortgage loan
- PennyMac: Can I do a mortgage recast with any principal payment amount?
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction