 Debtless
The short answer
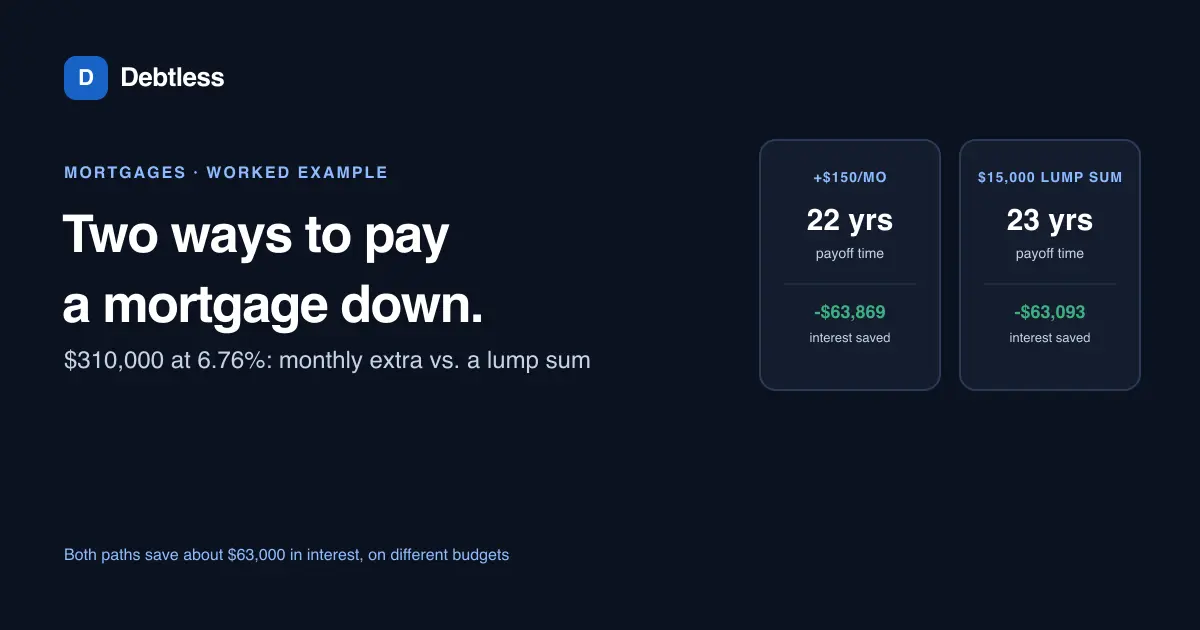
A mortgage calculator models paying down your loan faster in two main ways: adding a fixed extra amount to every monthly payment, or applying a one-time lump sum to the principal. On a $310,000 balance at 6.76% with 26 years left, a steady $150 a month saves about $63,869 in interest, while a $15,000 lump sum applied once and left alone saves about $63,093 while shortening the loan by a full extra year. Which one fits depends on whether you have the cash now or can commit to it monthly.
Two ways a calculator models paying down a mortgage
Total U.S. mortgage debt stood at $13.117 trillion in the second quarter of 2026, down slightly from the prior quarter, according to the Federal Reserve Bank of New York, meaning more households than usual made real progress paying balances down rather than just paying interest. A mortgage calculator's pay-down feature is how you can model that same progress on your own loan before you commit to it.
There are two common approaches. The first adds a fixed extra amount, say $150, to every regular payment. The second is a one-time lump sum, from a bonus, an inheritance, or a sold asset, applied to the principal all at once.
Worked example: $310,000 at 6.76% with 26 years left
Start with a $310,000 balance at 6.76% APR (Freddie Mac's 30-year average for the week of September 10, 2026) with 312 months, 26 years, remaining. The required payment on that schedule is $2,112.44 a month, and paying only that amount costs $349,082.15 in total interest over the rest of the term.
- Confirm your current balance and remaining term from a recent statement before running either scenario.
- Model the steady extra-payment path first, since it doesn't require cash on hand today.
- Then model a lump sum you could realistically apply now, and compare the two payoff dates side by side.
- Check with your servicer that any extra amount, monthly or lump sum, posts to principal immediately rather than sitting as a prepayment on next month's bill.
Path one: a steady $150 a month
Adding $150 to the $2,112.44 required payment every month pays the loan off in 264 months, 22 years, 4 years earlier than the original schedule. Total interest drops to $285,213.17, a savings of $63,868.97 for a payment increase most household budgets can absorb gradually.
Path two: a $15,000 lump sum, with or without a recast
Apply $15,000 to principal once, dropping the balance to $295,000, and keep making the original $2,112.44 payment. The loan pays off in 276 months, 23 years, one year earlier than the original schedule, with total interest of $285,989.55, a savings of $63,092.60, close to what the steady monthly path produced.
A servicer will sometimes offer a recast instead: after the $15,000 lump sum, it recalculates a lower required payment over the same 312-month term rather than shortening the term. On this balance, that recast payment comes to $2,010.23, about $102 less each month, with total interest over the full term at $332,191.08. According to Experian's explainer on mortgage recasting, a recast keeps your original rate and term and doesn't require the underwriting a refinance does, but it lowers your payment instead of shortening your timeline.
Choosing between the two paths
The steady $150-a-month path and the $15,000 lump-sum-without-recast path land within about $800 of each other in total interest saved on this example, which is closer than most people expect. The real difference is cash flow: one asks for $150 more every month starting now, the other asks for $15,000 once.
The same steady-versus-lump-sum comparison applies to any debt you're paying down, not just a mortgage, and how lenders apply payments is worth reading before you assume an extra payment posts the way you expect.
$310,000 balance, 6.76% APR, 26 years remaining
| Required only | +$150/month | $15,000 lump sum | |
|---|---|---|---|
| Months to payoff | 312 | 264 | 276 |
| Time to payoff | 26 years | 22 years | 23 years |
| Total interest paid | $349,082.15 | $285,213.17 | $285,989.55 |
Calculated with the standard amortization formula. Lump-sum scenario assumes the original payment continues after a one-time $15,000 principal payment, without a recast.
Worked example · illustrative numbers
Example: what a recast changes versus what it doesn't
On the same $295,000 post-lump-sum balance, choosing a recast instead of keeping the original payment lowers the bill to $2,010.23 a month but stretches full repayment back out over all 312 remaining months, for $332,191.08 in total interest.
Skipping the recast and keeping the $2,112.44 payment finishes in 276 months instead, at $285,989.55 in total interest, a difference of $46,201.53 in interest for the same $15,000 lump sum. A recast is worth it if the goal is a lower monthly bill; skipping it is worth more if the goal is finishing early.
Put this into practice with Debtless
Debtless can't process a recast or a lump-sum payment on your behalf, since it doesn't connect to your servicer or move money. What it does is take the balance, rate and extra payment you enter, monthly or one-time, and show the new payoff date and interest total for your mortgage alongside every other debt in the free iPhone app.
Common questions
Is it better to pay down a mortgage with a lump sum or steady extra payments?
On the example here, they land within about $800 of each other in interest saved, so the better choice usually comes down to cash flow. A lump sum works if you have it now; steady extra payments work if you'd rather commit gradually.
What is a mortgage recast, and does it save money?
A recast applies a lump sum to your balance and lowers your required payment over the same remaining term, without changing your rate. According to Experian, it doesn't shorten your payoff timeline the way skipping the recast and keeping your old payment would.
Does every mortgage servicer offer a recast?
No. Recasting is common but not universal, and it isn't available on every loan type. Ask your servicer directly whether it's offered before you plan around it.
Can a mortgage calculator model both a lump sum and monthly extra payments?
A calculator that lets you enter an extra monthly amount can usually model a lump sum too, by treating it as a one-time extra payment in the first month. [Debtless's payoff calculator](/debt-payoff-calculator/) uses the same extra-payment logic across every debt you track.
Sources & further reading
- Federal Reserve Bank of New York: Household Debt and Credit Report, Q2 2026
- Freddie Mac: Primary Mortgage Market Survey
- Experian: What is mortgage recasting?
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction