 Debtless
The short answer
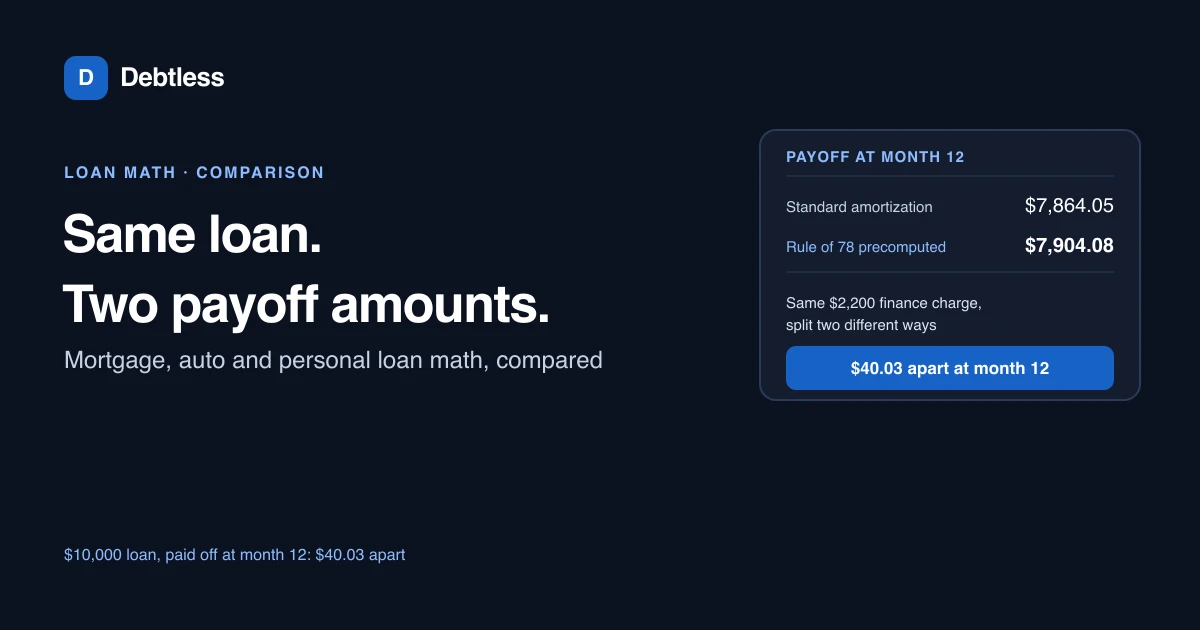
An amortization repayment calculator shows how a fixed payment splits between interest and principal over the life of a loan, assuming the balance declines the same way every month according to a standard formula. That assumption holds for a mortgage and for most personal and auto loans issued today, but it doesn't hold for an older-style precomputed loan that divides up its finance charge using the Rule of 78 instead. On a hypothetical $10,000, 48-month loan, that difference adds up to about $40 more owed if you pay it off after a year than a standard amortization calculator would show.
What an amortization repayment calculator assumes
Every standard amortization calculator, including a mortgage tool, works the same way underneath: it charges interest on whatever balance is left at the start of each month, then applies the rest of the fixed payment to principal. According to the CFPB, early payments on a mortgage go mostly toward interest, and the split gradually shifts toward principal as the balance shrinks, purely because interest is calculated on a smaller number each month.
That single assumption, interest computed fresh on the current balance every period, is what makes a calculator's math trustworthy at all. It's also the assumption that a small category of older loan contracts doesn't actually follow.
Where the assumption holds: mortgages and most loans issued today
Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed rate at 6.95% for the week of September 17, 2026, and every calculator built around that kind of loan, a mortgage tool, a personal loan calculator or an auto loan calculator, assumes the standard declining-balance method by default. Search for a plain mortgage amortization tool and most results are single-purpose calculators built around one variable at a time, the kind compared in Mortgage Payoff Calculator: Simple vs. Full Plan, but the underlying interest math in nearly all of them is identical.
The mortgage version of this same accuracy question, checking that a calculator's inputs match your real statement, is covered in plainer terms in House Payoff Calculator: A Plain-English Explainer. None of that changes the fact that the calculator itself is modeling the loan correctly; the risk there is bad inputs, not a mismatched method.
Where it breaks: precomputed, add-on-interest loans
A smaller category of loans, mostly older retail installment contracts, doesn't calculate interest fresh each month. Instead, the total finance charge is set in advance and divided across the loan term using a sum-of-digits schedule called the Rule of 78, which assigns more of that interest to the early months than a true declining-balance calculation would.
Federal law limits how far this can go. Under 15 U.S.C. § 1615, a creditor computing an early-payoff refund on a loan longer than 61 months has to use a method at least as favorable to the borrower as the actuarial method, the standard amortization approach, which in practice rules out the Rule of 78 for anything past that length. Shorter loans in some states can still use it, so it hasn't disappeared entirely.
Why this only shows up if you pay off early
If you pay a Rule of 78 loan to term, on schedule, the two methods land on the same total interest and the same final payment. The gap only opens up if you pay off before the end of the term, since the Rule of 78 has already assigned more of the total interest to the payments you've already made than a declining-balance calculator would assume at that point.
That's the whole reason the distinction matters for a repayment calculator specifically: two loans can show identical monthly payments and identical total interest on paper, and still require different amounts to close out the same month if one of them precomputes its interest.
Hypothetical $10,000 loan, 48 months, paid off after 12 payments
| Standard amortization calculator | Rule of 78 precomputed payoff | |
|---|---|---|
| Payoff balance at month 12 | $7,864.05 | $7,904.08 |
| How interest is assigned | Recalculated on the declining balance each month | Front-loaded using a sum-of-digits schedule |
| Legal for terms over 61 months | Always | No, per 15 U.S.C. § 1615 |
Hypothetical example: a $10,000 loan with a $2,200 total finance charge over 48 months, illustrating how the same total interest produces two different early-payoff amounts depending on which method the contract specifies.
Worked example · illustrative numbers
Example: the same $10,000 loan, two payoff amounts
Take a hypothetical $10,000 loan over 48 months with a $2,200 total finance charge, for a payment of $254.17. A standard amortization calculator, working out an implied rate of about 10.1%, puts the remaining balance after 12 payments at $7,864.05.
A Rule of 78 contract carrying the same $2,200 finance charge assigns interest by the sum of the digits from 48 down to 1. After 12 payments, only 666 of the total 1,176 digits remain, so the unearned-interest rebate is smaller than a declining-balance calculation would give, and the actual payoff comes to $7,904.08, $40.03 more than the amortization calculator showed.
Put this into practice with Debtless
Debtless's payoff calculator uses the standard declining-balance method for every debt you enter, a mortgage, a car loan or a credit card alike, the same assumption almost every modern amortization repayment calculator makes. It won't flag a precomputed Rule of 78 contract on its own, since that detail lives in your loan agreement, not in the balance and rate you type in, but it will keep an accurate running payoff date once you know which method actually applies.
Common questions
Do all loans amortize the same way?
Most do today. A standard amortization calculator assumes interest is recalculated on the declining balance every month, which matches how mortgages and most current auto and personal loans work. A smaller category of older, precomputed retail loans uses a different method instead.
How do I know if my loan uses the Rule of 78?
Check your loan agreement for the term "precomputed" or "add-on interest." If neither term appears and the contract describes simple interest on the outstanding balance, a standard amortization calculator applies.
Is the Rule of 78 illegal?
It's restricted, not banned outright. Federal law under 15 U.S.C. § 1615 prohibits it for consumer loans longer than 61 months. Some states restrict or ban it for shorter loans too, but rules vary.
Does this affect my mortgage?
No. Mortgages amortize using the standard declining-balance method, the one every mortgage calculator, including Debtless's, is built around. The Rule of 78 distinction mainly applies to older short-term retail installment contracts.
Sources & further reading
- CFPB: How does paying down a mortgage work?
- Freddie Mac: Primary Mortgage Market Survey
- Cornell LII: 15 U.S.C. § 1615, rebates upon prepayment
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction