 Debtless
The short answer
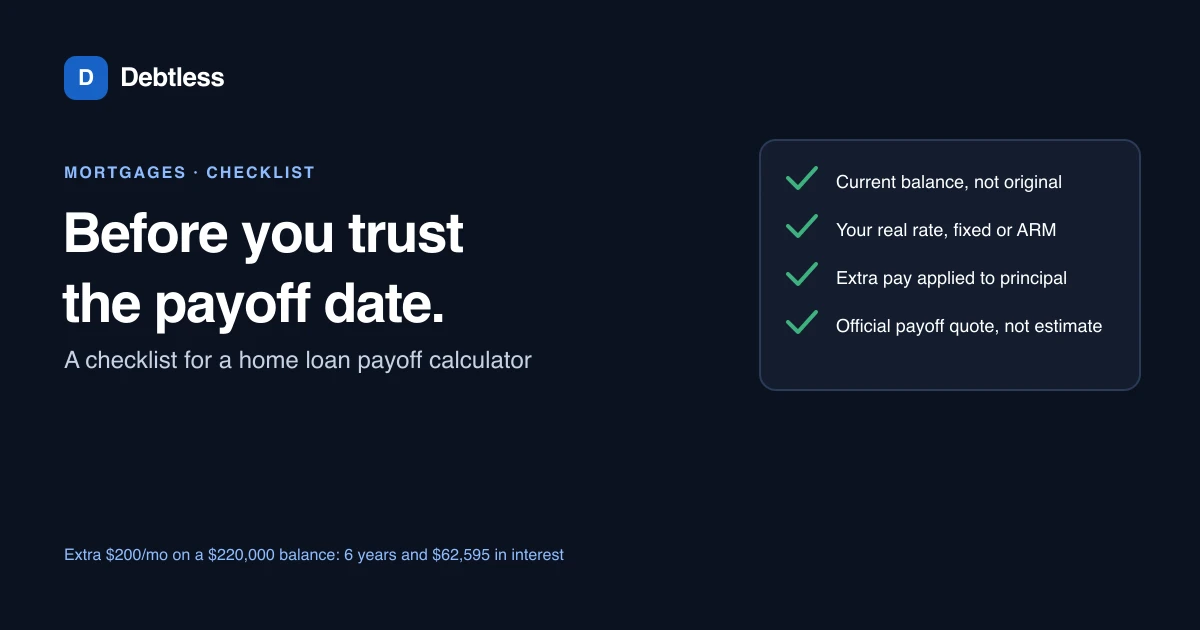
A home loan payoff calculator estimates a new payoff date from your current balance, rate, remaining term and any extra payment, but it's only as accurate as what you enter. Before trusting the date it shows, confirm you used your current balance and remaining term, not the original loan amount and 30-year term, and confirm any extra payment is actually applied to principal. On a $220,000 balance at 6.5% APR with 25 years left, an extra $200 a month cuts about 6 years and roughly $62,595 in interest off the loan, but only if the servicer applies it correctly.
What a home loan payoff calculator needs to get right
A payoff calculator answers a narrower question than a payment calculator: given what you owe right now, how fast does that balance reach zero. That means it needs your current balance and current rate, not the numbers from your original loan documents, plus how many months are actually left and whether you plan to add anything extra.
Getting any one of those wrong changes the answer more than most people expect, especially on a loan with decades of amortization still ahead of it.
The checklist: six things to confirm before you trust the number
Run through these before you act on a payoff date, whether the calculator is a lender's, a third-party tool, or Debtless's payoff calculator.
- Enter your current balance, from a recent statement, not the amount you originally borrowed.
- Enter your remaining term in months, not the original 15- or 30-year term, unless you haven't made a payment yet.
- Use your actual current rate. If you have an adjustable-rate loan, confirm whether it has reset since you last checked.
- If you're adding an extra payment, confirm with your servicer that extra amounts are applied to principal immediately, not held and applied to next month's regular payment.
- Keep escrowed taxes and insurance out of the payoff figure; a payoff calculator should only be working with the loan balance itself.
- If you're actually closing out the loan soon, request an official payoff statement from your servicer rather than relying on the calculator's estimate for the final number.
Worked example: what an extra $200 a month actually does
Take a $220,000 balance at 6.5% APR with 25 years (300 months) remaining. The required monthly payment on that schedule is $1,485.46, and paying only that amount takes the full 300 months and costs about $225,636.73 in total interest.
Add $200 a month in extra principal, and the loan is paid off in about 228 months, roughly 19 years, cutting 6 years off the timeline. Total interest drops to about $163,041.64, a savings of around $62,595.09, all from one consistent extra payment applied to principal every month.
Where a calculator's estimate and your servicer's payoff quote diverge
A calculator gives you an estimate based on the numbers you typed in on a given day. An official payoff statement from your mortgage servicer includes per diem interest, accrued daily between your last payment and the date the servicer receives your payoff funds, plus a "good through" date after which the amount changes.
Federal mortgage servicing rules generally give your servicer seven business days to respond with an accurate payoff statement once you request one in writing, according to the CFPB. That written request, not a calculator's estimate, is the number you actually wire or send at closing.
Testing a calculator before you rely on it
Before trusting any payoff calculator with your real numbers, run it against a simple example you can check by hand first, using a round balance and a rate you can verify with a calculator app. If it returns the payoff date you'd expect, you can trust it with your actual balance.
Debtless applies this same math across every debt you're tracking, not just a mortgage, and the guides section has more on building a full payoff plan around it.
$220,000 balance, 6.5% APR, 25 years remaining
| Required payment only | With extra $200/month | |
|---|---|---|
| Months to payoff | 300 | 228 |
| Time to payoff | 25 years | About 19 years |
| Total interest paid | $225,636.73 | $163,041.64 |
Calculated with the standard amortization formula; results assume the extra payment is applied to principal every month without interruption.
Worked example · illustrative numbers
Example: reading a payoff statement's per diem line
Say a servicer's payoff statement lists a payoff amount of $214,300 good through a date 10 days out, with a per diem interest charge of $38.75. If your closing slips 4 days past that date, the actual amount due rises by $38.75 x 4 = $155, to $214,455.
That daily accrual is exactly what a calculator's one-time estimate can't capture, since it depends on the specific day funds arrive at the servicer, not the day you requested the statement.
Put this into practice with Debtless
Debtless can't request an official payoff statement from your servicer, since it doesn't connect to your bank or your loan account. What it does is take the balance, rate and payment you enter and show how a change, like a $200 extra payment, moves your projected payoff date, for a mortgage alongside every other debt in the free iPhone app.
Common questions
What's the difference between my loan balance and my payoff amount?
Your balance is what a statement shows as of its cutoff date. Your payoff amount is what you'd owe on a specific future date, including per diem interest accrued since your last payment, which is why the two numbers rarely match exactly.
How do I get an official mortgage payoff statement?
Request one in writing from your servicer. Federal servicing rules generally require an accurate payoff statement within seven business days of that request, according to the CFPB.
Does an extra principal payment really save that much interest?
It can, especially early in a loan. On the $220,000 example here, a consistent $200 extra per month saves roughly $62,595 in interest and cuts about 6 years off a 25-year remaining term, as long as the extra amount is applied to principal right away.
Can Debtless calculate my mortgage payoff the way a lender's tool does?
Debtless doesn't issue official payoff statements; your servicer is the only source for that exact, date-specific number. [Debtless's payoff calculator](/debt-payoff-calculator/) is built to estimate your payoff timeline and show how an extra payment changes it, alongside every other debt you're tracking.
Sources & further reading
- CFPB: Your mortgage servicer must comply with federal rules
- CFPB: How does paying down a mortgage work?
- Freddie Mac: Primary Mortgage Market Survey
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction